
The unluckiest equity investor vs the boring debt investor
Unluckiest Investor vs a “Boring” Debt Investor, Who wins over 35 years?
Most would instinctively say: “Equity investor, obviously.”
After all, we’re told:
“#Equities give 12% returns.”
“#Debt instruments are a wealth destroyer.”
So I decided to test this theory.
🧮 The Setup
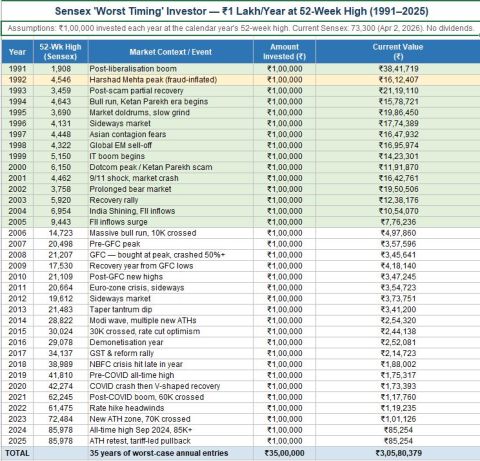
Investor 1: Invests in equities at the worst possible time every year
Investor 2: Invests in safe instruments like Reserve Bank of India bonds
📊 The Result (Surprising)
After 35 years:
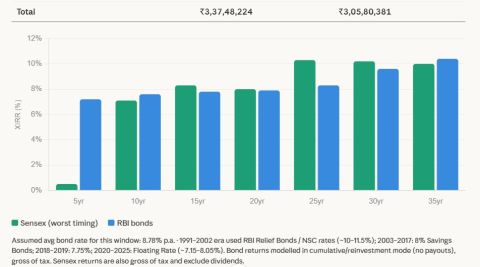
👉 Debt investor corpus ≈ ₹3.37 Cr
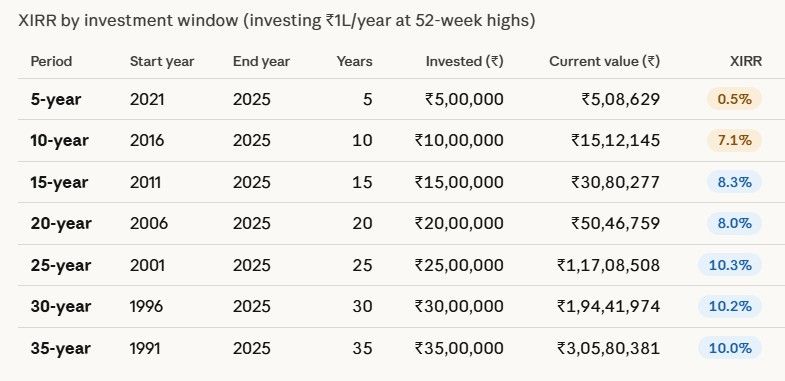
👉 Equity (worst timing) ≈ ~₹3.05 Cr
Difference: ~₹32 Lakhs
Yes, equities can catch up with dividends included…
But that’s not the real point.
🧠 Look deeper for the Unluckiest Investor!
- 5-year XIRR → ~0.5%
- 10-year XIRR → ~7%
- 15-year XIRR → ~8.3%
Even in equities, timing can distort outcomes massively! There is no guarantee that long-term investments will give 12% plus returns, as our #Finfluencers keep saying, in every other post!
⏳ Context matters
We often forget:
In the 90s, debt instruments gave 10–12% returns
Even the most abused debt instrument, PPF, delivered ~12% between1986 and 2000!
🤔 So what’s the key takeaway of the analysis?
Not that: ❌ “Debt is better than equity.”
But that:👉 Narratives can be misleading!
“Equity always wins” → Not always (depends on behavior)
“Debt destroys wealth” → Not always (at least data doesn't agree with this)
Always remember, #PersonalFinance isn’t about chasing the “best” asset.
It’s about: Finding the right balance and the products you can stick with through cycles, volatility, and time! #MentalPeace is very important when dealing with money.
⚠️ A few Caveats
- Future debt returns are unlikely to match the past, with the governments becoming more fiscally responsible
- Equity returns may moderate as markets mature
- This is a scenario analysis, not a recommendation
Beauty with stats, you can prove almost anything with selective data.
But in real life, Consistency beats both perfect timing and perfect narratives!