
Want to become a mutual fund distributor now? Think again
Recently, a friend told me he wanted to become a #MutualFund Distributor (MFD), inspired by a similar story as covered in the picture attached, and asked for my advice.
With the rapid rise in awareness about #DirectMutualFunds and their much lower costs, my answer was simple: Don’t!
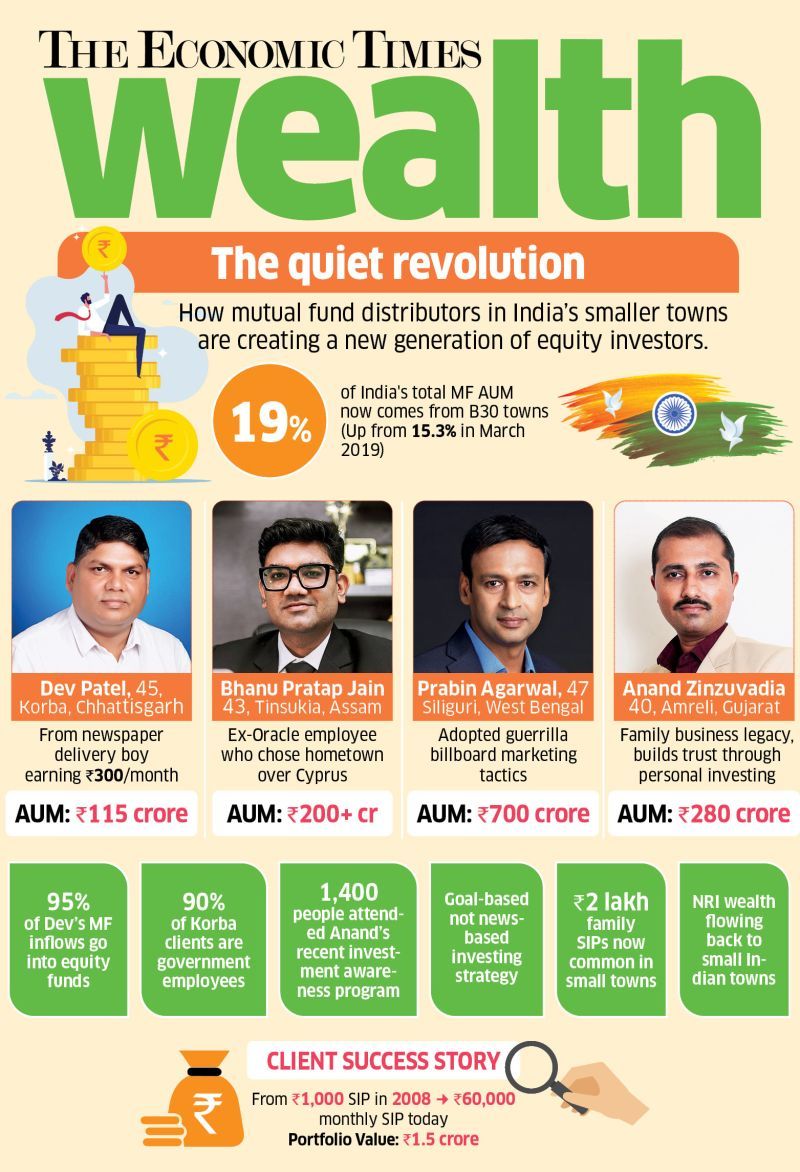
Here’s why:
Direct MFs now make up 30%+ of total AUM, and the share is rising fast.
With eKYC, mobile apps, and MFCentral, investing from your sofa is easier than ever. MFDs would have a tough time growing the market.
Direct mutual funds have a lower expense ratio, thus providing better returns. Sooner or later, investors would understand that and move away from regular funds!
Where do MFDs still thrive?
Tier 2 & smaller cities, where trust in a person outweighs trust in a system.
Unfortunately, this often leads to mis-selling like -
- Pushing #NFOs (higher commissions)
- Creating portfolios with high overlap
- Recommend active funds over index funds
- Discourage withdrawals (since it stops their trail commission)
Since the target segment is generally financially illiterate, they typically don't understand these concepts and get swayed away by a graph that shows 15% returns in a straight line fashion!
Then my friend smiled and said, “What if I become an MFD and invest my own money through my code?”
I told him: “As a new MFD, your commission will be <0.5%, you’ll pay tax on that income, and remember, expense ratios are ~1% higher than Direct. You can do the math!”
Sometimes, the numbers speak louder than words!
Do you invest via an MFD and invest in Regular funds, or does your money earn more by investing in Direct funds?
And feel free to reach out to me, in case you are looking for any advice on #PersonalFinance, #Taxation, #CreditCards optimization.