
An advisor who never lets you withdraw
Recently, a friend reached out with a rather unique problem:
“My #MutualFund #Advisor never lets me withdraw money!”
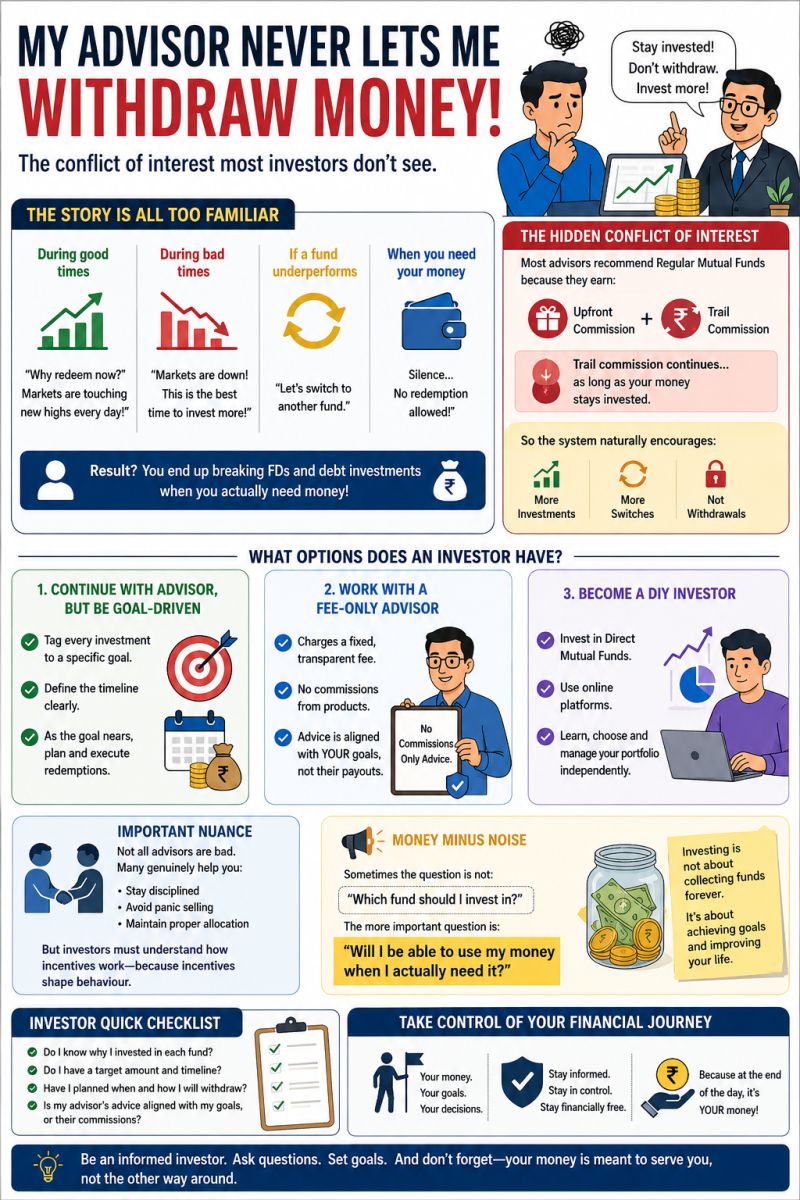
During #bull markets, the response would be:
“Why redeem now? Markets are touching all-time highs every day, they will go up further!”
During corrections:
“Markets are down! This is the best time to invest more, average your purchase value!"
If a fund underperformed: “Switch to another fund.”
But one thing remained constant: Never let the money leave the ecosystem.
Whenever he actually needed money for a Vacation, an emergency, a family expense, or a Down payment, he was forced to liquidate:
- Fixed Deposits
- Debt investments
- Savings
…while #Equity Mutual Funds remained untouched 😄
Sadly, his case is not unique.
This highlights one of the biggest conflicts of interest in the Mutual Fund distribution industry.
Most advisors/distributors recommend Regular Mutual Funds, because they earn:
- Upfront commissions
- Trail commissions (continue as long as your money stays invested)
Which means, the system naturally incentivizes:
- More investments
- More SIPs
- More switches
…but not necessarily: Goal completion or redemption.
And over time, many investors unknowingly start treating Mutual Funds like “Money that should never be touched.”
But investing is not about collecting funds forever.
Investments exist to achieve goals, create financial security, and improve life quality.
At some point, Money has to come back into your life.
So what options does an investor have?
1. Continue with the Advisor, but define #goals clearly
Every investment should have a purpose, a timeline, and most importantly, a withdrawal strategy.
And as the goal approaches, Redemption should start gradually.
2. Work with a #Fee-Only Advisor
Here: The advisor charges a fixed fee, with no commissions from products. Thus, a lower conflict of interest.
3. Become a #DIY Investor
With Direct Mutual Funds, Online platforms, and Public information availability, many investors today can manage simple portfolios independently. Index investing has made portfolios simpler for many!
PS - Not all advisors are bad; many genuinely help investors to stay disciplined and avoid panic selling.
But investors also need to understand how incentives work and if the advice is beneficial for the Advisor or for the investor!
Have you ever faced a similar situation with an advisor or distributor?
How did you handle it?
And in case you are looking for any help with #PersonalFinance, #Taxation, or #CreditCards optimization, feel free to connect.