
What US rate caps could mean for credit cards
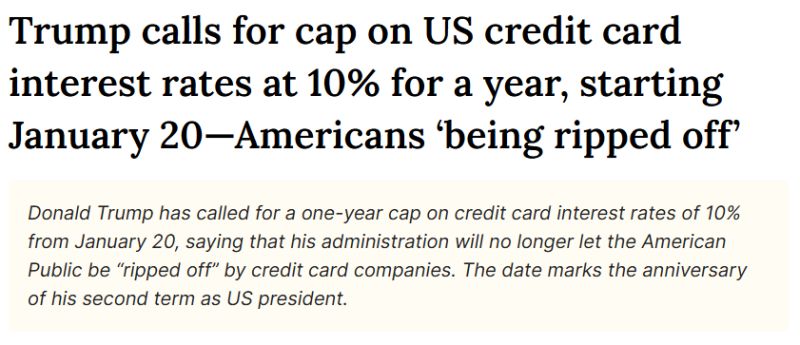
Latest developments in the US could fundamentally change how #CreditCards work.
The credit card business is largely funded by “#revolvers” - customers who pay only the minimum due and incur steep interest charges, sometimes as high as ~40%.
These charges help banks:
- Fund #CreditRisk
- Absorb #NPAs
- Cover sourcing costs
- Subsidize #Rewards for full-pay customers
Now, if interest rates are drastically capped, the entire model will need a reset.
What could change?
1️⃣ Stricter #Risk models
Risk scores may be rewritten, leading to tighter card issuance. Expect mass cancellations, especially for lower-credit-score customers.
2️⃣ Reduced #CreditLimits
Even if cards survive, limits may not. Banks will look to reduce exposure aggressively.
3️⃣ Rewards take the biggest hit
“#Deadbeat customers” (those who pay in full every month) are often reward hunters. With interest income shrinking, free lounge access, accelerated points, and cashback models may no longer be sustainable.
The unintended consequence
Reduced access to formal credit could push vulnerable users toward unorganized loan sharks, often at similar or higher rates, but with zero consumer protection.
What could have been a better approach?
While 40% sounds high, it is a global industry norm for unsecured revolving credit. Banks could have proactively acted to avoid such an action by -
📘 #FinancialEducation
Many users believe credit cards are meant for minimum payments. Clear, mandatory counselling after defaults could go a long way.
📊 Continuous #RiskAssessment
Creditworthiness isn’t static. I’ve seen people load up on cards during high-paying jobs and retain them years later, even after income collapses. Banks need ongoing evaluation, not one-time underwriting.
✂️ #Frugality
Do we still need physical plastic cards in a Tap & Pay world?
There are multiple areas where costs can be cut to protect margins without squeezing interest income alone.
What about #India?
If a similar regulation ever comes to India, it would be disruptive.
Credit card penetration is still low!
Customer acquisition has been driven largely by generous rewards!
A cap on interest rates would almost certainly collapse reward structures.
And with Gen Z already deeply hooked to #UPI, the Indian credit card industry could be in for a real shock.
Interesting times ahead.