
How to fix debt and free up monthly cash flow
“How can I fix my debt and increase my monthly cash flow?”
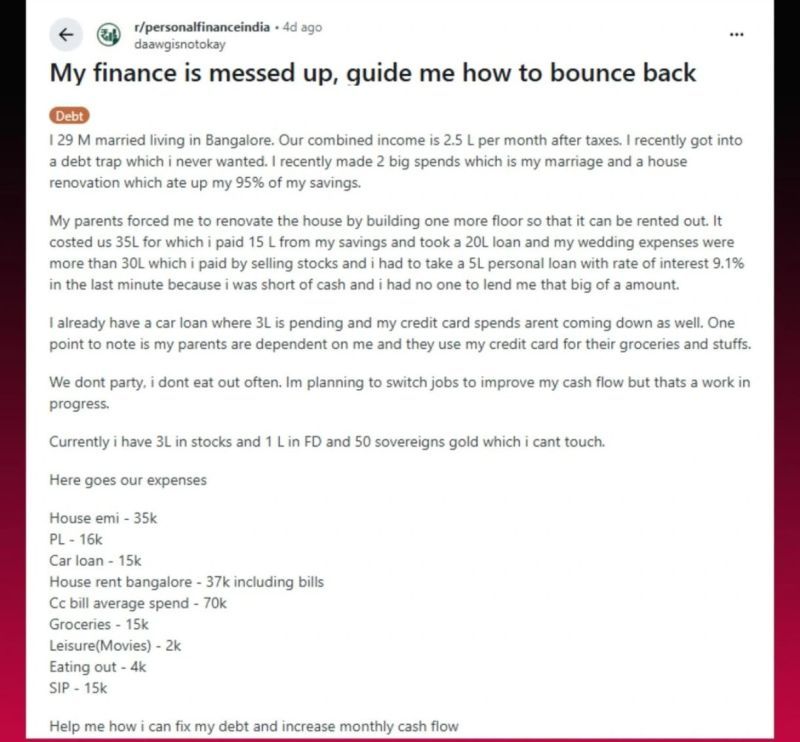
This was the question someone asked on Reddit.
Surprisingly, a lot of the commentary on SocialMedia is focused on blaming him, his parents, and the fat Indian Wedding!
Very little is on what he should actually do now.
Let’s focus on the real solution here.
1. Consolidate the expensive debt
He has multiple EMIs. Can he leverage the 50 sovereigns of gold he has?
Gold loans typically have a lower interest rate than personal and car loans.
Opt for that, prepay the costliest loans, reduce the monthly burden!
2. The ₹70K credit-card bill needs serious investigation
Rent, groceries, eating out, and movies are already separately listed.
Where exactly is that ₹70K going?
Before cutting everything else, find the leak.
3. Optimise the salary before chasing another salary
He's planning to switch jobs.
But that will take some time!
But there is something he can do immediately:
Check the salary structure.
New vs. Old tax regime.
Check the PF deduction.
Meal benefits.
Tax-efficient components offered by the employer.
Any other company benefits.
Sometimes the easiest way to improve cash flow isn't earning more.
It's keeping more of what you already earn.
4. Pause the SIP temporarily
While most finfluencers say “never stop your SIP”, you will lose the compounding effect!
Sadly, there is no compounding in Equities!
He has only ₹1L in FD and ₹3L in stocks while carrying multiple loans and uncertain cash flow.
Divert the ₹15K SIP towards building a proper emergency fund.
Equity investments are for the long term.
Emergency funds are for emergencies.
One unexpected event should not force him to take another personal loan or swipe a credit card.
5. Build the long-term cash-flow engine
Finally, the biggest lever isn't cutting ₹2K from movies.
It's increasing income.
Upskill.
Reskill.
Look for promotions.
Explore better opportunities.
A ₹10K expense reduction helps once.
A ₹30K increase in monthly income can change the trajectory every single month.
And one more thing.
Looking at his numbers, there is a clear gap between the earnings and expenses mentioned!
Income: ₹2.5L/month
Listed expenses including SIP: roughly ₹2.09L/month
So there is still around ₹41K/month of headroom on paper.
Many people really don't know where their money is going!
That 2k movie expense could be 5k; that 4k eating out could be 10k!
We really don't know till we track!
Though I am generally against tracking expenses row-item-wise, for folks who are in dire situations, an itemized tracker helps!
If you were in his shoes, what would you do first?
If you’re dealing with a financial situation that feels more complicated than it should, feel free to connect.