
UPI at 10: the rise and fall of Paytm
As #UPI completes a decade, this is the second post in the series.
👉 The story of #Paytm
There was a time when Paytm was synonymous with the #DigitalEconomy in India.
- #Wallet transactions were soaring
- It rode the 2016 Indian #demonetization wave brilliantly
- While others reported UPI numbers, Paytm reported total digital transactions and was miles ahead of competitors
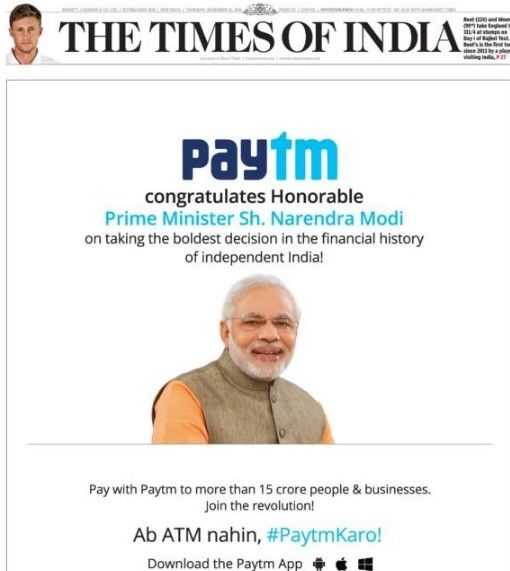
The Big Bet: Wallet over UPI
Paytm was clearly bullish on wallets, and the logic wasn’t wrong:
👉 #Monetization – #MDR on wallet transactions (unlike UPI)
👉 #Control – End-to-end ownership → faster, fewer failures
👉 #Float income – Earnings on idle wallet balances
For years, it worked beautifully, then the tide turned!
Three major shifts changed everything:
1️⃣ Rising Costs
Users loaded wallets via #CreditCards
Triple benefits: CC reward points + credit period + Paytm cashback
👉 But someone had to bear the cost.
Paytm paid MDR to card networks
Eventually started charging for wallet loads
Card issuers also reduced rewards, while many even added additional fees
👉 The loop broke.
2️⃣ UPI Took Over
Zero cost for merchants (no MDR)
Direct bank transfer (no preload friction)
Massive Cashbacks from the players
👉 Both merchants and users shifted rapidly
3️⃣ #Regulatory Tightening
Wallets became easy channels for #fraud
Regulations tightened significantly
👉 The product lost its edge
The Outcome, from category creator Paytm, now ranks third, far behind PhonePe and Google Pay, in terms of UPI transactions!
💡 My #Eureka Moment with Paytm
During peak demonetization, I went out for dinner, and when it came to payment, 'Houston, we have a problem!'
- POS machine down (remember the era of poor network when Rain falls!)
- Cash is useless (thanks to Demonetization)
- UPI is not mainstream yet (The Government just started promoting UPI, PhonePe has just launched the app in Aug 2016, while GPay aka Tez is not even born!)
We were stuck in an embarrassing position!
Then it clicked:
👉 Load Paytm wallet → transfer to the restaurant manager
Reluctantly, he agreed (had to explain, you can pay the electricity bill using this amount).
Soon, others in the restaurant followed the same approach!
That’s when I realized:
This wasn’t just a recharge app anymore, and my usage changed overnight. #P2P transactions zoomed!
Many of us would have had similar stories from the Demonetization era!
Could the story be different? In hindsight, every story could be.
But what Paytm did that time seems to be a correct strategy. UPI was a new product, with a lot of unknowns, while Wallet was an established one, with Paytm spending crores on establishing the ecosystem and a clear revenue path. Even now, the pure play UPI apps don't have the right monetization path and eventually hang on to loans to make money!
No one knew that UPI usage would zoom, and it would become the default transaction app for crores!
For many years, for my kid, money used to mean #PaytmKaro!