
After two years, a new card I actually enjoy: slice UPI credit card
After almost 2 years, I finally got a new #CreditCard…
And surprisingly, I am genuinely loving the experience 😄
The slice #UPI Credit Card!
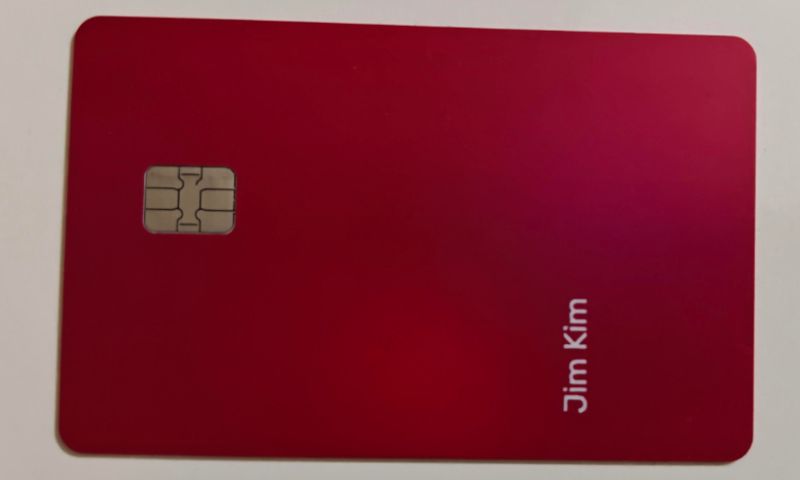
The last couple of years have honestly been quite boring for Credit Card enthusiasts. Most headlines were about:
- Devaluations
- Reduced reward points
- Lounge access cuts
- Spend-based milestones
And almost every “new launch” was just another Secured Credit Card (#FixedDeposit Backed), which never really excited me.
So when I heard Slice was offering an unsecured UPI Credit Card, I couldn't help but hit the apply button.
Though there was one catch 😄
The app forces users to open a Zero Balance #SavingsAccount alongside the Credit Card.
Initially, I wasn’t too thrilled about that. But the desperation to get one more Credit Card in my collection won 😄
And I ended up having both a Slice Credit Card and a Slice Bank Account.
It’s been around 2 months now, and the product experience has been quite solid till now.
Things I genuinely liked:
- Flat 1% #cashback on all UPI Credit Card transactions
Whether it’s ₹10 chai or ₹10,000 electronics, the cashback structure remains the same
- Higher #rewards possible
If you accumulate more points, effective rewards can go even higher in some cases. In addition, via Play and Win, the rewards percentage can go up slightly
- Instant #redemption
No thresholds. Rewards can be redeemed immediately after transactions as a deposit to the Bank account.
This psychologically feels much more satisfying than waiting endlessly to redeem points 😄
- Weekly “Spark” offers
Extra cashback opportunities keep refreshing on popular merchants like #Swiggy, #Zepto, #BookMyShow, etc!
- Savings Account #Interest rate linked to #RepoRate
This part was quite interesting. The Savings Account interest is equivalent to the #RBI Repo Rate and gets credited daily! Yes, daily credit, no need to wait for Monthly or Quarterly credits!
- #Lifetime Free + Zero #Forex Markup
This combination alone makes the card attractive for many users.
What I initially thought would become: “Just another addition to my Credit Card collection,” has quietly become my default UPI Credit Card!
And one thing Slice has done well is that it still keeps UPI at the center of the experience.
The homepage itself feels like a #payments app first, and a banking product second.
The UX clearly follows a “#LessIsMore” philosophy!
Of course, there are things to watch, like every fintech product:
- Reward structures can change
- Devaluations can happen
- Features can evolve over time
So it’s important not to over-optimize your financial life around any single card!
Slice is definitely a refreshing change from traditional bank experiences!
Have you tried Slice yet? If not, join via my referral link here -
https://lnkd.in/ggkRk4rR
And in case you need any help on #PersonalFinance, #Taxation, or #CreditCards optimization, feel free to connect!