
Ashneer Grover, BharatPe and the UPI MDR noise
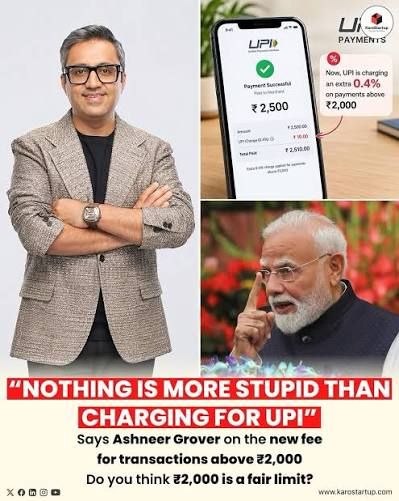
#UPI got an #MDR. #AshneerGrover got a field day.
Wondered if he would have said the same thing if he were still at #BharatPe!
But here's the thing:
Most of the noise around UPI MDR is unnecessary!
The situation is not as alarming as portrayed by the #Influencers community!
So, as I always do, let's remove the noise and look at what actually changes.
Who actually pays the MDR?
Not you.
The new framework applies a 0.4% MDR on eligible P2M UPI transactions above ₹2,000, with a ₹300 cap.
And small merchants in the P2M category those receiving less than ₹1 lakh per month through UPI remain protected, irrespective of the individual transaction amount!
So your neighbourhood tea, panipuri, or small kirana shop isn't suddenly getting an MDR bill because you paid ₹2,500.
What about #Amazon, #Zomato & other organised merchants?
They are the ones more likely to feel it.
But MDR itself isn't new.
Credit cards have been charging merchants MDR for years, and these players have been paying the same!
So UPI nominal MDR shouldn't come to them as a shock!
What about Stocks & Mutual Funds?
There is a separate 0.02% MDR for eligible capital-market transactions, capped at ₹300.
Invest ₹1 lakh through UPI?
That's ₹20 of MDR for the merchant.
The average SIP value in the country is ₹3000, resulting in an MDR of 60 paise!
Whether platforms absorb it, pass it through another fee, or negotiate their economics remains to be seen.
What could change?
Most #influencers are saying people would move to #CreditCards for large purchases. But this would be counter-productive for the merchants; remember CCs have a much higher MDR (2-3%)
Could this have been done differently?
I've said this before:
Why not introduce a tiny #VPA-level fee, with #NPCI setting a maximum and payment apps free to discount it?
That could have created:
Transparency + competition + a sustainable revenue model + kill the noise!
https://lnkd.in/gJDXfWwN
Instead, we now have a fairly complicated merchant-level mechanism that banks, PSPs, payment aggregators, and acquirers will have to operationalise.
And that's where the real questions begin: how to implement the MDR!!!
How will merchants be classified?
How will monthly thresholds be tracked?
How will refunds and reversals work?
How will the ecosystem reconcile these charges?
How would Rupay CC transactions on UPI rails be accounted for?
The headline says: UPI charges introduced.
The reality is more nuanced:
Consumers aren't being charged (P2P remains free). Small merchants are largely protected. The MDR applies to specific merchant transactions.
So, before changing how you pay because of a headline, remove the noise
That's the whole point of #MoneyMinusNoise.
Would this change your preferred payment method?