
FDs are still a solid option for many retirees
Contrary to what many #Finfluencers say, #FixedDeposits (FDs) are still a solid option for many #Retirees.
Not because they give the highest returns, but because they offer:
- Simplicity
- Predictability
- Familiarity
And in retirement, these matter more than chasing extra % returns.
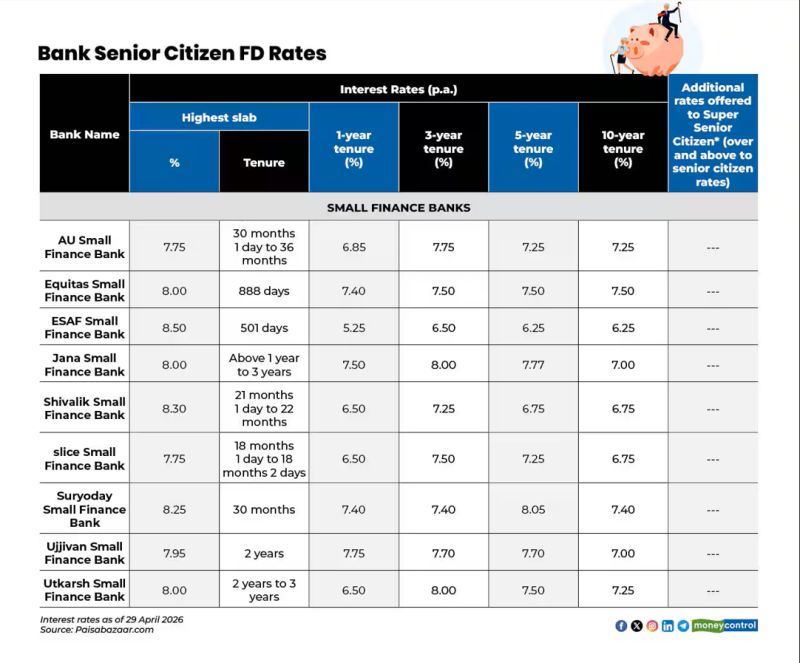
Some #SmallFinanceBanks are offering up to ~8.5% for #SeniorCitizens.
Tempting, but that’s where caution comes in.
What should senior citizens check before opening an FD?
1. Physical presence matters -
Choose a bank with a nearby branch, even if the rate is slightly lower.
Because when something goes wrong: Accessibility > Extra interest
2. Avoid unnecessary intermediaries
Opening FDs via third-party apps may feel easy
But during issues, they redirect you to the bank anyway!
3. Understand Deposit Insurance and Credit Guarantee Corporation (#DICGC)
Insurance limit = ₹5 lakh per depositor per bank
Includes: Savings + FD + interest + any other deposits (RDs etc)
Pro tip: Joint accounts (e.g., with spouse) are treated differently than individuals → can increase coverage
4. Check digital access
Ensure the FD can be broken online (app / net banking)
Because emergencies don’t wait for banking hours.
5. Don’t create one large FD
Instead: Split into multiple FDs (laddering)
Benefits: Lower penalty on premature withdrawal, helps with better liquidity management
6. Plan for taxes
Interest is taxable. Smart planning = better post-tax returns
Higher rates often come with: Higher perceived risk!
While the Reserve Bank of India (#RBI) ensures overall system stability, avoid over-exposure to any single small bank
Because: You may get your money back, but not many would tell you when. Avoid unnecessary stress during the Golden days!
Are FDs part of your #RetirementPlanning?
If you are looking for any help with #CreditCards optimization, #Taxes, #FIRE, do reach out!