
“Vijay sir keeps 50% in the bank!” Have his money first
A friend recently forwarded me #Vijay’s #Portfolio breakup and said:
“Bhai, you never let me keep money in #bank deposits… see Vijay sir, he has more than 50% assets in banks!”
I replied: “The day you have money like him, you can do whatever you want.” 😄
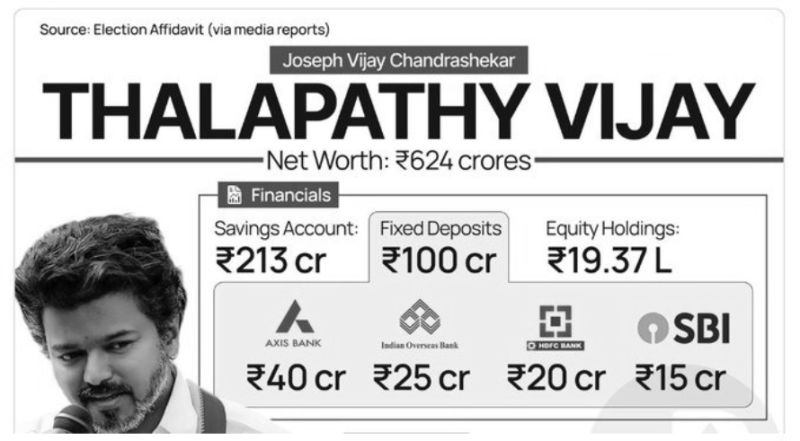
And that’s one of the biggest problems in #PersonalFinance.
People compare portfolios… without comparing circumstances!
Someone with Massive #wealth and multiple #income streams can afford to think very differently.
The #Risk profile is completely different from a person who is still building wealth!
Over the years, while discussing portfolios with multiple folks, I’ve seen this repeatedly.
Some say, “If a famous fund manager can keep 90% in #equities, why are you suggesting that I reduce the exposure?”
While others say, "Why are you pushing me toward equities? #FD is a safer option.”
Reality lies somewhere in between; for most people, building wealth, neither extreme works.
Too aggressive: One bad phase can destroy confidence!
Too conservative: #Inflation silently destroys wealth!
The key is calculated risk!
Your allocation should depend on:
- Your income stability
- Responsibilities
- Risk tolerance
- Goals
- Age
- Existing corpus
For a person with a massive portfolio, he can take blind Risks or be Conservative, since at that stage, Survival is already guaranteed.
Maximum risk? Their children saying: “Kaash maa-baap ne yahan invest kiya hota…” 😄
Personal Finance is called 'PERSONAL' for a reason.
Getting inspired by others is good, but blindly copying them is dangerous!
Do you follow a disciplined path, or are you influenced by others and keep changing?