
SIP loans: keep your investments, pay the interest
#SIPLoans!
This was a new term I was introduced to last week.
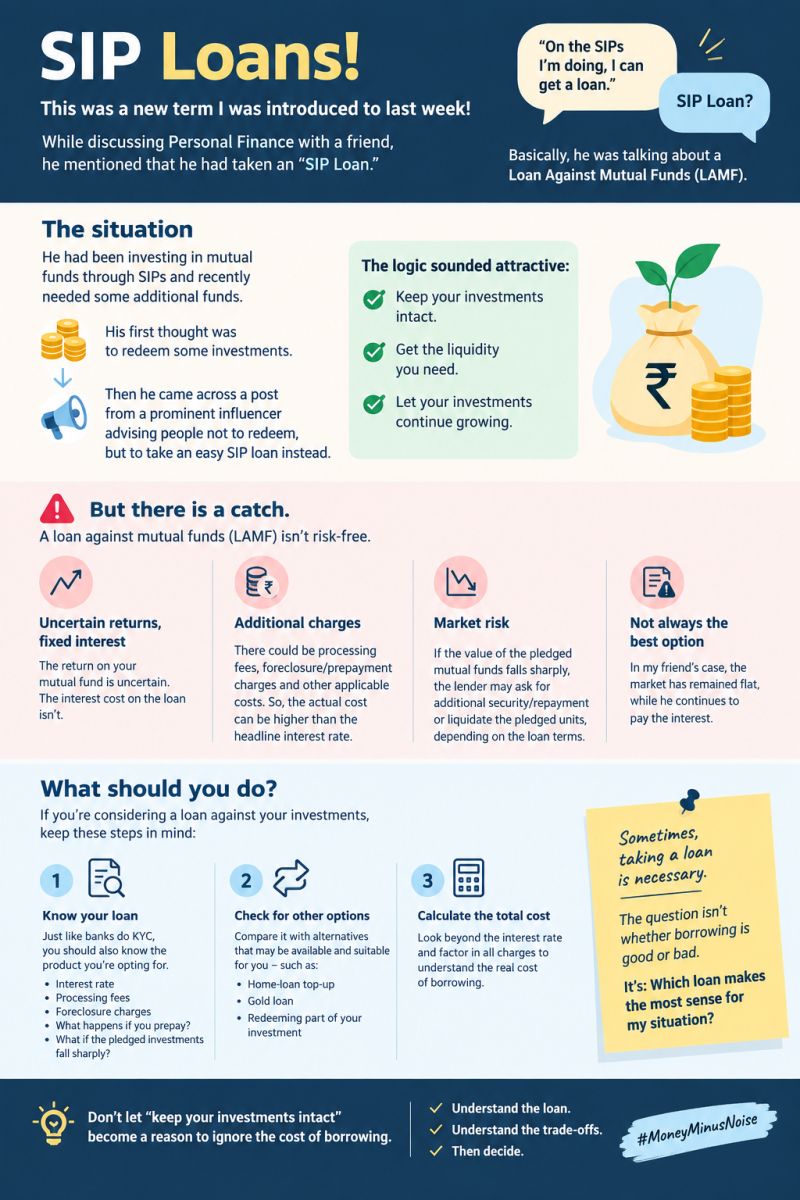
While discussing #PersonalFinance with a friend, he mentioned that he had taken an “#SIP Loan.”
I asked, “What's that?”
“On the SIPs I'm doing, I can get a loan.”
Basically, he was talking about a Loan Against Mutual Funds (#LAMF).
He had been investing in #MutualFunds through SIPs and recently needed some additional funds.
His first thought was to redeem some investments.
Then he came across a post from a prominent influencer advising people not to redeem their investments, but to take an easy SIP loan instead.
The logic sounded attractive:
Keep your investments intact. Get the liquidity you need.
Let your investments continue growing.
Sounds good. But there is a catch.
The return on your mutual fund is uncertain. The interest cost on the loan isn't.
In the current situation, the market has remained broadly flat, while he continues to pay interest on the loan.
Run through these quick checks before you opt for a LAMF:
1. Look for the hidden costs.
The headline interest rate isn't your only cost. Check the processing fees, the prepayment penalties, and foreclosure charges.
2. Watch the market drop.
If the stock market crashes and your fund value falls sharply, the lender won't wait for a recovery.
They will ask you for immediate cash, or they will forcefully sell your mutual fund units at rock-bottom prices to get their money back.
3. Compare it to simple redemption.
We are told that selling our funds is a sin. But sometimes, redeeming a small portion of your investment and paying a one-time tax is vastly cheaper than dragging out a costly loan.
4. Check for alternatives.
Single-click loans are easy but may not be the best. Check for alternatives like a top-up home loan; gold loans might offer a lower overall total cost of borrowing
Sometimes, taking a loan is necessary.
What matters is understanding which loan is right for you.
Understand the loan.
Understand the trade-offs.
Then decide.