
What a sane FIRE portfolio actually looks like
What should a sane #FIRE portfolio actually look like?
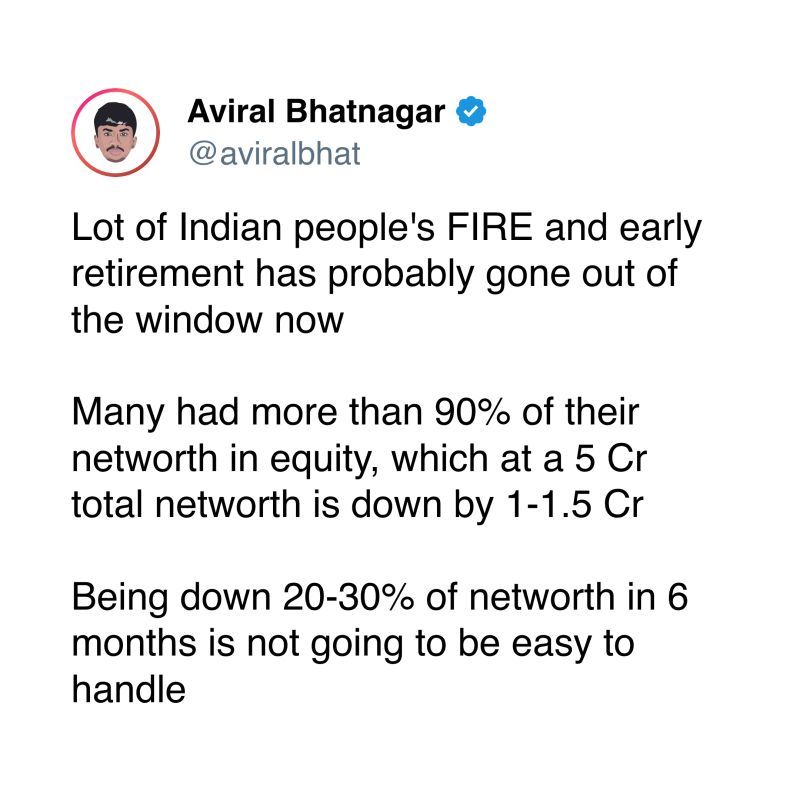
If you listen to the internet, the answer can be insane:
Go 90% or 100% into equity!
Assume a clean 12% straight-line return and wait!
But real life doesn't work like an Excel sheet.
For me, FIRE isn't about maximizing equity exposure.
It’s about building enough wealth without taking so much risk that a single market crash derails the life you’ve already planned.
A sane FIRE investor thinks about #AssetAllocation, not just high returns.
Even when your retirement goal is decades away, keeping 90% of your net worth in equity leaves you incredibly exposed.
It also leaves you with very little room to maneuver.
Most seasoned investors I interact with keep their equity capped at no more than 60% to 70%, even for long-term goals.
Why?
Because a balanced split gives you the power to rebalance.
When the stock market crashes, you don't panic or try to guess the bottom.
You simply move money from your steady debt bucket into cheap equity to reset your targets.
When the market rallies, you lock in profits by moving money back to safety.
That is the true beauty of having an allocation.
You don't predict the market.
You rebalance.
And as financial independence gets closer, the need for this stability becomes critical.
Imagine quitting your job and watching your equity-heavy corpus take a sudden 30% hit right as your salary stops.
That is when Sequence-of-Returns Risk stops being a textbook term and becomes a devastating reality.
If you want a truly resilient FIRE structure, stop looking at trending portfolios and follow a simple, multi-phase framework:
The Accumulation Phase (Years away from FIRE):
Maintain a steady 65-70% Equity / 30-35% Debt split.
This gives you aggressive growth but provides a massive cash buffer to comfortably buy the dips when the market corrects.
The Transition Phase (~5-7 Years from FIRE):
Gradually dial equity down to 50%.
Concurrently, begin building a separate Bucket 0, a liquid cash bucket containing 3 years' worth of living expenses in ultra-safe fixed deposits or liquid funds.
The Withdrawal Phase (Living off the corpus):
Draw your monthly income strictly from your cash bucket.
This completely shields your remaining equity and debt investments, giving them time to recover from volatile market cycles without being forcefully liquidated to pay your bills.
The objective of financial freedom isn't to build the highest possible mountain of wealth.
It is to maximize the probability that your portfolio will successfully fund your life.
Those are two entirely different goals!
Filter the hype! Protect your baseline! Decide for yourself!
And if you need guidance on your FIRE journey, feel free to leave a comment!